

In 2023 we are expecting to see lots of changes when it comes to Paid Family and Medical Leave on both the state and nation-wide level. In this whitepaper, we break down the current landscape of paid leave programs and recommendations for employers to adopt and manage effective paid leave policies.
Title:
Senior Vice President and Co-Founder.
Joined Spring:
I was one of the original founders of Spring (alongside Karin Landry) back in 2004, as a spin out from Watson Wyatt Insurance & Financial Services, Inc.
Hometown:
I was born and raised in Golden Valley, Minnesota (Minneapolis area), but went to college in Wisconsin.
At Work Responsibilities:
I lead our absence management team, and work with employers of all sizes and industries and leading insurance carriers and administrators in the space. I also head up our Spring’s market research surveys and benchmarking.
Outside of Work Hobbies/Interests:
Being outside, going for walks; spending time with family, and of course, watching my kids play basketball.
Fun Fact:
One thing many people don’t know about me is that I actually use to run track in high school and led the 4×100 relay.
Describe Spring in 3 Words:
Interesting work & caring culture, I guess that’s actually 5 but that’s how I would describe Spring. The people all care about each other and have each other’s backs and support each other. We have a motivated team that is eager to collaborate.
Do You Have Any Children?
Yes, I have two beautiful children, my daughter is 17 and my son is 15.
Favorite Place Visited:
Greece, by land and sea! It has to be my favorite because of the history, beautiful architecture and amazing weather!
If You Were a Superhero, Who Would You Be?:
It would be Elastigirl from The Incredibles because her arms are so long and she can hold everybody. She can take care of everything!
the International Foundation of Employee Benefit Plans recently wrapped-up their 32nd Annual Health Benefits + Conference Expo (HBCE) in Clearwater Beach, Florida. The conference brought together healthcare and benefits professionals from a range of industries to discuss leading topics and share expectations for the future. Having heard such positive feedback about the event, Spring was glad to attend, exhibit, and speak at the conference. Below are some of our biggest takeaways.
1) Pharmacy Cost Containment
This year there was a lot of talk surrounding the price of prescription drugs and tactics employers can adopt to help control costs without cutting benefits. There are many factors influencing the high costs of pharmacy drugs, some of which include chronic disease prevalence, the aging population and the growing volume of specialty medications. Below are some of the top sessions focused on controlling Rx costs.
– Representatives from Express Scripts explained the upsides to working with a Pharmacy Benefit Manger (PBM) and how they can help address pharmacy policies in their session titled, “How to Work With Your Pharmacy Benefit Manager.”
– The CEO and Co-Founder of TruDataRx, Cataline Gorla, discussed how comparative effectiveness research (CER) is being used by other countries to decide which drugs work best for specific medical conditions, and how self-insured employers can save money with said data.
2) Addressing Chronic Conditions
According to the Center for Disease Control (CDC), 90% of the nation’s healthcare spending goes towards people with chronic and mental health conditions1. As chronic diseases are very common among the American workforce, employers have started implementing specific benefits and policies to address common conditions, such as diabetes and obesity. Some of the sessions around this topic that we found most interesting include:
– Speakers representing the Nashville Public School System explained how they were able to introduce free resources such as telenutrition and fitness center access to help combat obesity and other health disparities.
– Dr. Mudita Upadhyaya from St. Jude Children’s Research Hospital presented on prevention strategies to address mental health and obesity in a pre- and post-COVID world; and why a mixed approach may be best.
– The Diabetes Leadership Council’s CEO, George J. Huntley spoke on diabetes and chronic disease risk management strategies, including medicines and technology that can help patients manage and prevent the disease.
3) The Future of Healthcare & Benefits
In recent years we have seen a great shift in the healthcare and benefits industry; we saw a great increase in telehealth, mental health resources, new/alternative types of paid leave, including sick leave and more. As we transition to a post-COVID world, we expect the evolution to continue. Below are some of the top trends professionals believe we will face in the coming years.
– Our Senior Vice President, Teri Weber, presented on market forces employers can utilize to meet future absence management challenges. Her session listed techniques employers can adopt to improve day-to-day administration of disability, absence and accommodations.
– In a session titled “Innovative Health Care Models—The Future of Direct Primary Care,” the presenter explained how many employers are changing to value-driving healthcare models to boost access and reduce costs.
– A session titled “Breaking the PTO Mold, Without Breaking the Bank,” reviewed how typical Paid Time Off (PTO) programs can be altered to better support employees’ well-being and financial health.
– The final session of the conference spotlighted how the pandemic has led to an increase in personal, economic and other stressors and has had a drastic impact on mental health, substance misuse and addiction. Attendees were informed on how they can implement workplace solutions that address these issues as well as identify warning signs.
The warmer weather was certainly a bonus, but the insights we gleaned and connections we made were what will keep us coming back to the HBCE conference. We want to thank IFEBP and our fellow colleagues who took the time to share their experience, stop by our booth, and make the energy so positive.
1https://www.cdc.gov/chronicdisease/about/costs/index.htm
As seen in the New England Employee Benefits Council (NEEBC)’s blog.
Last year around this time, I gave a year-one progress report on the Massachusetts Paid Family and Medical Leave (PFML) program, as it had finished its first year of paying out benefits to eligible workers. Since then, the MA PFML program has continued to mature and adjust according to experience, and, around New England, Connecticut has had PFML benefits available for one year, and there are related updates from Rhode Island, New Hampshire, Vermont and Maine to report.
Massachusetts: A Year in Review
In fiscal year 2022 (July 1, 2021 – June 30, 2022), the Massachusetts Department of Family and Medical Leave (DFML) experienced1:
– Over 112,500 applications, with 20% being denied
– 59% of applications were related to medical leave, 31% for bonding, and 10% to care for a family member
– Only 32 approved applications for military exigency leave and 7 approved applications to care for a service member
– Claimants aged 31-40 had the most approved claims (40%) and more than 1.5 times as many women had an approved leave (61% of claims), compared to men (35% of claims)
– Average weekly benefits were $793.55 for family leave and $754.84 for medical leave
– Turnaround times from the time the application was submitted to an initial decision was a median of 17 calendar days
– Average duration of leave was 12 weeks, assuming a 5-day work week
– Total benefits paid was equal to about $603 million (an increase of about 245% from FY21 which accounted for January 1, 2021-June 30, 2021)
In 2023, Massachusetts will be updating maximum benefit amounts and reducing total contributions.
– The maximum weekly benefit is increasing to $1,129.82, effective 1/1/2023. This is an increase of about $45 from the 2022 weekly maximum. For any employees who may have leave that runs from 2022 into 2023, the weekly benefit that was determined when leave was approved will continue. The new maximum will not be applied until there is a new MA PFML leave application.
– Contributions, however, will be reduced in 2023. The total contribution is decreasing from 0.68% to 0.63%, for employers with 25 or more covered individuals. The medical leave contribution will be 0.52%, with employers funding 0.312% and employees responsible for up to 0.208%. The family leave contribution will be 0.11%, with employers able to collect the total contribution from employees. Employers with less than 25 employees are not required to submit the employer portion of premium.
The financial earnings requirement was also updated in 2023. Employees must have earned at least $6,000 and 30 times the PFML benefit amount during the base period to be considered eligible for MA PFML.
Connecticut: First Year Activity
Connecticut has now had PFML benefits available for 1 year. During the first six months of the program2:
– Over 44,127 applications, with 40% being denied of those that received a decision
– 44% of approved applications were related to medical leave, 29% for bonding (own child and adoption/foster care), 18% for pregnancy/childbirth, and 9% to care for a family member
– Only 15 applications were approved for family violence, 12 for organ and bone marrow donation, and 2 for qualifying exigency
– Claimants aged 26-41 had the most filed claims (53%) and more than double the number of females applied for leave (28,814), compared to males (14,213)
– Average weekly benefits paid were $562.01
– Average approved duration of leave was 6.79 weeks
– Total benefits paid was equal to about $81 million
– Almost 137,000 businesses have registered with the CT Paid Leave Authority and claim applications have been received from every city and town in the state
Based on the experience in the state in 2022, Connecticut is not making any major changes to the program in 2023. However, the social security contribution and benefit base increased to $160,200 on January 1, 2023, and CT minimum wage increases to $15/hour on June 1, 2023, which will impact benefit and contribution amounts.
Please note that the program has some key differences when compared to MA PFML, such as the availability of leave for organ and bone marrow donation, as well as leave related to family violence. Differences in benefit amounts, leave duration, and eligibility conditions also make it difficult to directly compare CT and MA PFML experience.
Other New England Updates
Massachusetts and Connecticut are not the only New England states to be seeing PFML progress. Rhode Island has an established temporary disability insurance program (TDI), which was the first statutory disability program in the country, established in 1942. In 2014, they became the third state to offer family leave benefits through temporary caregiver insurance (TCI). In addition, the state does not allow private plans, making the model slightly different than other PFML programs in the region. On January 1, 2023, a few updates to TDI and TCI became effective. The state’s taxable wage base increased to $84,000, which will impact the contribution calculation. The benefit duration also increased to 6 weeks, from 5 weeks in 2022. Finally, the financial eligibility conditions claimants must meet increased so that employees must have paid at least $15,600 in the base period or meet the alternative conditions wherein they earned at least $2,600 in one of the base period quarters and base period taxable wages equal to at least $5,200.
A new outlier is New Hampshire’s first-in-the-nation, state-sponsored voluntary plan where NH employers and eligible NH workers can purchase a paid family and medical leave plan through the state’s insurance carrier. New Hampshire selected MetLife as its insurance partner and began paying benefits on January 1, 2023.
Similarly, Vermont spent 2022 developing a voluntary program to be administered by The Hartford, their selected insurance carrier. Beginning July 1, 2023, state employees will be covered under the program, with other private and public employers with 10 or more employees eligible for coverage in 2024, and small employers and individuals able to purchase coverage in 2025.
Maine also made strides in developing the structure of their state mandated PFML program. Maine created a commission to study PFML programs and to propose a PFML model for the state, which kicked off in May 2022. Policy recommendations are expected to be presented to the Legislature in 2023.
Are You Up to Speed?
As the PFML landscape continues to evolve at the local, state and federal leaves, policies need to be monitored on an ongoing basis. Employers should ensure they are compliant with the requirements of each individual leave program, as differences exist between all established paid family and medical leave policies. If any of your employees are impacted by a state PFML policy, organizations should review plans, policies, and processes to confirm they are in line with any legislative changes. To do so, the following checklist can be followed:
– Register in any new states where employees are located, if required
– Ensure contributions are being collected appropriately
– Update employee notices and benefit documentation, as appropriate
– Confirm employee count to determine if any changes to contributions are required
– Review private plan strategies based on previous year experience and changes to contributions
– Renew private plans as appropriate
– Validate company sponsored leave programs coordinate with PFML to the extent possible
If you need assistance ensuring PFML compliance or to assess the optimal plan set up for your organization, Spring’s consultants are happy to help www.springgroup.com
Paid Family and Medical Leave continues to be a confusing point for employers, compounded by new legislation being proposed at a seemingly constant pace. As leaders in the disability and absence management space, we are dedicated to staying on top of updates around PFML, among other areas. After a busy year in that regard, with another on the horizon, we wanted to share this brief overview.
In 2022, there was more movement towards state PFML laws being passed after decreased activity in previous years, largely due to the COVID-19 pandemic. For example:
- Delaware and Maryland both passed laws establishing PFML programs
- Virginia established insurance rules, allowing carriers in the state to provide insured PFML plans to clients
- Colorado and Oregon began collecting contributions on 1/1 and have been working to ensure they are prepared to do so, while establishing other rules for the effective administration of PFML
- New Hampshire worked to develop their voluntary PFML program selecting MetLife as its insurance partner and began coverage on 1/1/2023
- Vermont selected The Hartford as its insurance partner for its voluntary PFML program
- Maine made strides in developing the structure of their state mandated PFML program
In 2023, we expect continued activity. Pennsylvania and Michigan have outstanding proposals for PFML, which will likely be decided upon in 2023, one way or another. Additional states may also put forward proposals in upcoming legislative sessions.
In addition, and as seen in the updates below, states with existing legislation continue to make adjustments to their PFML programs. Adjustments to contributions and benefits are typically expected, most commonly, but not always, at the end of the calendar year.
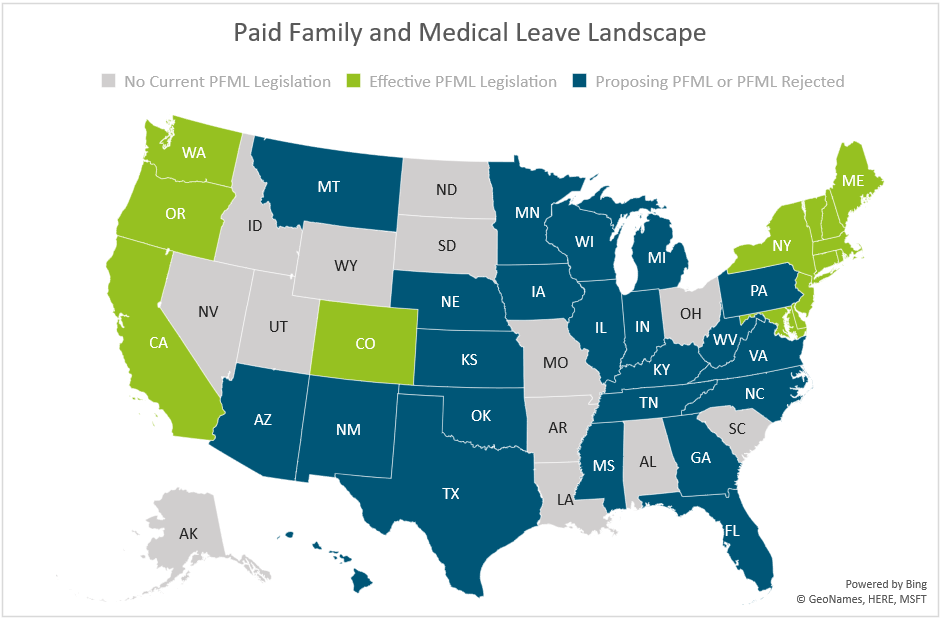
The map below shows a summary of states with existing PFML legislation and programs in place, those who have proposed legislation without it being passed, and those that have not had any activity related to PFML in recent years.
Massachusetts
In 2023, Massachusetts will be updating maximum benefit amounts and reducing total contributions.
The maximum weekly benefit is increasing to $1,129.82, effective 1/1/2023. This is an increase of about $45 from the 2022 weekly maximum. For any employees who may have leave that runs from 2022 into 2023, the weekly benefit that was determined when leave was approved will continue. The new maximum will not be applied until there is a new MA PFML leave application.
Contributions, however, will be reduced in 2023. The total contribution is decreasing from 0.68% to 0.63%, for employers with 25 or more covered individuals. The medical leave contribution will be 0.52%, with employers funding 0.312% and employees responsible for up to 0.208%. The family leave contribution will be 0.11%, with employers able to collect the total contribution from employees. Employers with less than 25 employees are not required to submit the employer portion of premium.
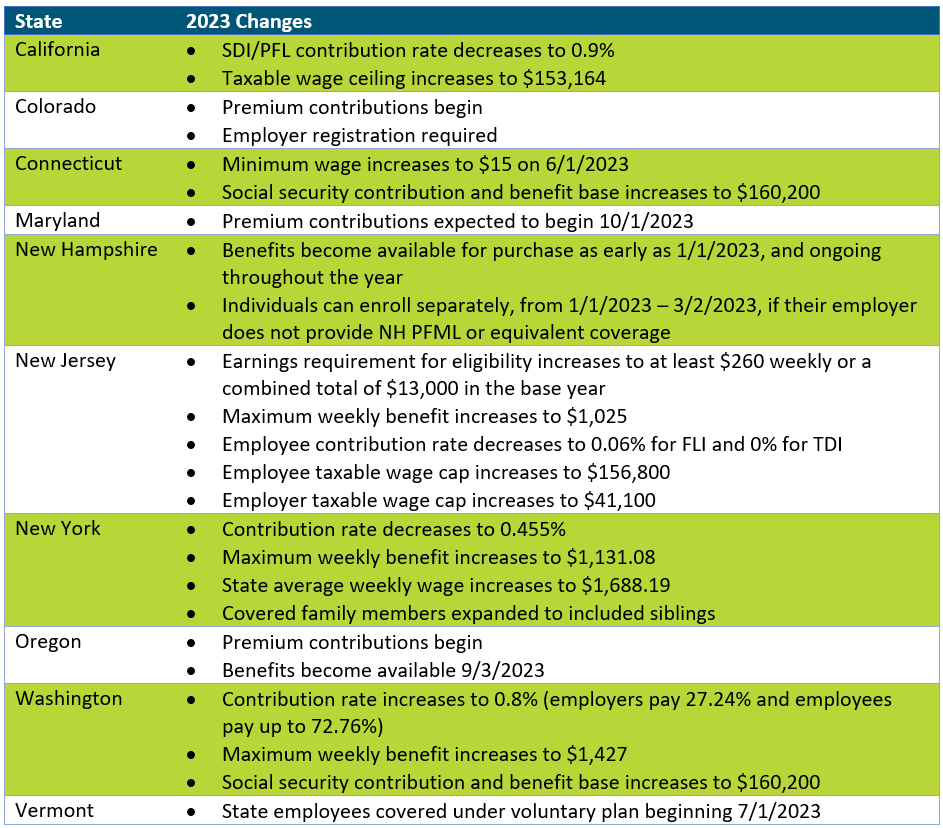
Other State Updates
Other states have made updates to their programs effective January 1, 2023, unless otherwise noted below. Some states may make changes off calendar year (e.g., District of Columbia, Rhode Island), which are not included if they have not yet been released.
Recommended Approach
Employers should review their PFML plans, policies, and processes to confirm they are in line with any legislative changes. To do so, the following checklist can be followed:
– Update employee notices and benefit documentation, as appropriate
While formal notices may not always be required, especially if contributions are decreasing, communicating updates to employees is recommended, especially if the change will impact their pay. Most states provide sample notices that can be customized to fit an employer’s needs. Keep in mind that there may be timing requirements in place (e.g., 30 days in advance).
– Confirm employee count to determine if any changes to contributions are required
Some states require contributions from both employers and employees however do not require employer contributions from “small” employers. This definition of small varies by state (e.g., less than 25, less than 50 employees). Confirming the total number of employees will verify the contributions being remitted to the state are accurate.
– Review private plan strategies based on previous year experience and changes to contributions
Whether or not a private plan is an ideal method for an employer to provide PFML to employees may vary from year to year. This can largely be based on the cost of a private plan versus going with the state plan, but the employee experience also plays a major role. From a cost perspective, a private plan, in most states, will be based on that employer’s leave experience. If an employer has high PFML incidence rates, insurance carriers or TPAs may charge more than is required to be paid under the state plan. From an employee experience perspective, having to file PFML claims to the state and what are often concurrent disability, FMLA or other leave claims to the employer or its vendor partner, can be confusing and require more effort for both employees and employers. While the driving factors will vary by employer, both cost and employee experience should be considered.
– Renew private plans as appropriate
When a private plan is in operation, states may require these be renewed at certain intervals. Massachusetts, for instance, requires this annually, while Connecticut only requires it every three years, unless a material change to the plan is made. Employers should review the timing of their private plan approval and guarantee it is up to date.
If you need assistance ensuring PFML compliance or assessing the optimal plan set up for your organization, Spring’s consultants are happy to help.
It is estimated that ~44 million Americans are experiencing long COVID symptoms. During a recent Spring webinar, our SVP, Teri Weber was joined by a pulmonologist and a representative from Goodpath to review common long COVID symptoms and how it is impacting productivity and claims. You can access the webinar here.
Spring has been selected to help the Maryland Department of Labor (MDL) more effectively implement and administer the Family and Medical Leave Insurance (FAMLI) Program. Check out the press release here.
Our Senior Vice President, Teri Weber published an article explaining how employers can better gauge the efficiency of their leave management programs and highlight areas for process improvement using the secret shopper model. Check out the full article published by the Disability Management Employer Coalition (DMEC) here.
Coming out of our COVID haze, it can be difficult to remember a time when employers could be truly strategic and proactive without priorities evaporating due to lockdowns, staffing shortages, travel bans or taking a U-turn due to pressures in other areas of the business. The time is now to pivot back to your strategic plans related to employee benefits. We recommend the road to an optimal benefits program be lined with solutions to specific pain points and cultural considerations at your organization. However, I advise at least considering the following within your strategic roadmap to see if they are a fit and can close gaps within your current program.
1) Employee Surveys
Priorities within your workforce have likely changed considerably in the past two to three years. If you haven’t asked employees about their priorities related to employee benefits, it is time! Some of your more traditional benefits or office-affiliated perks that may have been linked to attraction and retention in the past are no longer a value add to employees. It is not enough to talk about perks and flexibility; needs must be better understood to ensure you are providing something that actually attracts and retains talent, instead of the
2) Lifestyle Accounts
Financial accounts within employee benefits are not new (e.g., a Flexible Spending Account), but recently employers have started using these account-based perks in different ways to fill a gap that exists in their offering while providing ultimate flexibility. These accounts are taxable but can be used within the parameters set by the employer. Organizations may use them to support just about anything, but common categories today include:
– Medical procedures that may not be covered within the medical plan (i.e., infertility services, elective procedures, etc.)
– Travel expenses for medical services
– Family-focused benefits (i.e., doula, etc.)
– Legacy wellness support (i.e., fitness equipment, fitness classes)
The beauty of these services is that they can be selected based on employee needs as well as organizational culture and budget.
3) Absence Policies and Processes
Diversity, equity, and inclusion (DEI) are at the top of the list of internal initiatives, and goals are uniquely defined based on how much progress has already been made. It goes without saying that DEI is critical to the success of all companies, but I think a key area of DEI that requires some additional attention is your corporate absence strategy. Over the past few years, organizations have developed additional absence policies around COVID-19 and Monkey Pox, but there has also been a large push toward more family-focused leave of absences surrounding bereavement, parental leave, and the like. It’s important that DEI initiatives within employee benefits focus not only on the services but also on the time off that may be required, and viewing this through the many lenses of your diverse workforce.
4) Oncology Support
As benefits professionals, we have worked diligently to identify point solutions for high-cost and highly disruptive conditions. While point solutions continue to be part of a strong strategy, most employers have or will see an increase in oncology prevalence and spend due, in part, to expensive treatments but primarily driven by disrupted or delayed care and screenings.
Initial concerns with COVID-19 not only decreased primary care visits but snowballed, as providers later had limited appointments available due to overwhelming demand, which has translated into undiagnosed cancers. Now as participants are getting back to their primary care physicians, many cancers have progressed further or upstaged, creating the need for more intense and complex treatment.
In addition to the direct cost of cancer care, employee productivity is significantly less after a cancer diagnosis, even if that diagnosis is within their extended family.
Spring encourages employers to seek a proactive and holistic approach to oncology support, including some or all the following:
– Monitor screening engagement
– Encourage prevention including reminders and other communications; consider incentives
– Educate and support initial and ongoing care decisions
– Concierge support
– Clinical support
Of paramount importance is to educate and engage employees before a diagnosis, so they know where to go for initial support. Those first few weeks after a diagnosis are critical to setting the stage for appropriate treatment and clinical review and/or second opinions. There are some free and buy-up options in the market provided by top-tier cancer care providers/facilities. Those have brand recognition and are designed to provide unbiased support but, in many cases, they also funnel patients to their service centers. Another consideration available is point solutions that are agnostic to cancer care providers/facilities and provide concierge support but do have an add-on charge, typically as a per employee per month (PEPM) or per referral model.
5) Healthcare Disparities
One of the most complex items that should be on your roadmap is to examine what healthcare disparities exist in your population. For starters, ensure multilingual communications are available to close healthcare gaps for those with language barriers. From there, it is important to begin to stratify your population – if your size warrants – and begin to examine if health outcomes are impacted by race, location, earnings, and/or other social determinants of health. This strategic initiative must be performed in collaboration with your insurers and third-party administrators and will take dedicated time to set a methodology and refine your findings over time. The key is to at least get started by looking at the data and talking about how you can improve your understanding of the current state to work toward better data in the future.
Setting the strategic plan for your employee benefit package should be customized to your organization’s priorities and complexities that are identified through claims experience and survey information. Given each organization has its own culture, demographics, and business priorities, it is impossible to set a perfectly standard list of considerations when it comes to your employee benefit strategy. But as you drive toward the best vision for your company – off in the horizon – be sure to stop along the way to check out these five hotspots of benefits planning.
Spring frequently helps employers assess different solutions, plans, and programs and build them into their roadmap. One client, edHEALTH, is currently organizing three solution committees to refine areas of opportunity and prioritize solutions based on demand and change readiness.